What are you doing with your abundant life?
When you’re saving & investing for financial independence, you’re focused on accumulating enough without sacrificing your quality of life. And if you’re still in the military, then you’re hoping to salvage a reasonable work/life balance.
You’re frugal without being cheap. (You try to avoid deprivation, although the military guarantees that you’ll have to endure it.) You try to align your mindful spending with your values. Your frugality reflects your goal of a sustainable lifestyle.
As you approach your FI, perhaps you’re already emulating Ramit Sethi’s Rich Life by spending extravagantly on the things you love— and cutting costs mercilessly on the things you don’t.
We keenly understand that financial independence also offers FREEDOM!! The freedom to control your time, to pursue your interests, and maybe even to choose challenging & fulfilling work on your terms. You’re seeking an optimal work/life balance, more quality of life, more family time, and less stress.
(Professional Depositphotos model.)
But what exactly does your life look like after you reach FI?
We can all recognize our FI lifestyle with ‘enough.’ We all know that the 4% Safe Withdrawal Rate covers the worst-case markets of the last century, and that we can use variable-spending tactics if necessary. (A “failure” of the 4% SWR computer simulation doesn’t mean that we humans will run out of money— only that we might have to change our spending for a year or two during the rest of our lives.) Meanwhile we can all recognize the wealth effect from watching our investments grow.
Yet once our assets grow past ‘enough’, then what do we do with abundance?
Financial advisors report in surveys that as many as 75% of their retired clients don’t spend enough money to match the plan which those clients have already analyzed, built, and approved with their advisor. Some clients are actually proud that they’re still saving money in their retirement— money which they’ll never need and will only benefit their heirs.
As you might imagine from my last few years of blog posts, retirement spending is a frequent discussion topic among the members of the Millionaire Money Mentors forum. Social media makes millionaires look competitive about spending money, but it’s actually the opposite. Many of the MMM members built their seven-figure wealth from high salaries with low spending, and we’re very good at accumulation.
Unfortunately the skills of building wealth have little to do with using it, which can lead to a scarcity mentality about retirement. We’ll “never earn that much money ever again”, and when we finally retire then we have to “make our assets last for the rest of our lives.” OMG, what if we need that money someday?!?
On the MMM forum, we frequently taunt each other about spending more money. The difference is that it’s not only about consumption— but gifting, philanthropy, and improving our quality of life.
Extravagance While You’re Pursuing Financial Independence
Here’s a recent forum question which stopped me in my tracks:
“When you’re living in abundance, do you have any extravagances you can share?!?”
I immediately flashed back to the early 1990s on Oahu, when my spouse and I were raising our toddler. An “extravagance” of those years was at the beach on Hickam Air Force Base, where we could rent a $10 pavilion. We’d stash all of our gear there while we were splashing in the shorebreak. Later we could cool off in the pavilion’s shade.
Don’t get me wrong: back then we were already keenly aware of the line between frugality and deprivation. Shortly after starting our family, we bought our first (used) car with air conditioning. As young adults we’d learned to live without A/C in a tradewind tropical climate, but we rookie parents quickly realized that it was essential to cool off our backseat toddler so that we could all enjoy the ride.
That pavilion splurge turned into a lifestyle expansion. Once we jumped on its hedonic treadmill, if the beach pavilions were sold out then it felt like deprivation when we were ‘stuck’ in full sun on the sand— even with hats and umbrellas.
As of mid-2026, my spouse and I have been retired for 24 years and we’ve reached our mid-60s. Our asset allocation (very high in equities) has grown faster than inflation– while our spending has grown slower than inflation. In addition, my spouse earned her own Reserve pension while I encountered some VA disability compensation. We’ve already had our spending dialed in for decades while our assets continued to ccompound. Now that we’re in our Medicare years and approaching Social Security, we can see that we’re not spending it fast enough.
We’re certainly not trying to Die With Zero— but we’d rather not die with money that could have been used to improve our lives or the lives of others.
We’re still frugal in some ways (conserving our environmental resources) but we aren’t depriving ourselves. We’re now deep into the abundance mindset.
Spoiler alert: if we do this right, over the next couple decades we’re going to give away another two million dollars. Along the way we’re going to spend the rest of our money on our entertainment or our self-insured long-term care expenses… in whichever order those happen to us.
But What If The Stock Market Tanks?

You get the point.
Before I share our abundance list, let me emphasize that we’re not stuck in lifestyle expansion. We could temporarily cut back our spending during a prolonged recession like 2000-02 or 2008-09– and in a heartbeat. My spouse and I were on active duty for two decades, and we can play an outstanding frugal defense even if we’re not deployed for months.
Having written that, we have more than enough. Even if the economy crashes into an extreme multi-year recession with a sloooow recovery, we still have enough. This is what happens when you’re 24 years into the 4% Safe Withdrawal Rate on an asset allocation that’s high in equities.
I’ll write about our abundance list and then dive into our ‘extravagances’— many of which we now view as quality of life. They’re ranked roughly in their personal value (to us) or their dollar value.
At the end of the list, we’ll add up the impact on our financial independence. (Another spoiler: not as much impact as I thought.) As we go through our list, you could indulge in the same analysis with your family to see what your abundance might look like during your financial independence.
Our Abundance List
Gifting.
Our top priority (in dollars) is gifting our family.
Pragmatically, we’re keeping our assets below our state’s (very low) estate-tax exemption. We’re nudging our progeny toward proficiency at managing ever-larger sums of money. (They’re doing great!) Someday they’ll manage our elder finances for us, and we don’t want them to be stressed by their financial caregiving on our behalf.
Yes, we might be the best parents (and grandparents) ever, yet there’s also our strong element of self-interest. We don’t want to inflict the pain on them that we felt when I had to abruptly take over my father’s finances during his dementia.
Our daughter and son-in-law receive their January gifts by transfers between our brokerage accounts. (So far so good.) The grandkid(s) have their money stashed in the usual places for minors: 529s, 530As, Roth IRAs, and UTMAs. (Gifting can fill up a 529 account very quickly and kids need earned income for their Roth IRA contributions.) Their parents make those decisions until the grandkids reach the age of maturity, but we all keep talking about the options.
My spouse and I are sharing their inheritance with a warm hand while we’re all still around to enjoy it together. We’re also testing whether we really can develop financial literacy in a third or fourth generation of dynastic wealth. I’d like to think that what worked with our daughter would also work with another generation, and I’ll enjoy hanging around long enough to see it happen. Check back here in another 20 years or so.
(More professional DepositPhotos models.)
We’re frequently asked “What if your descendants spend *your* money on their entertainment, or just waste it?”
We answer that we’re using our abundance as a tool for many age-appropriate discussions about financial literacy, budgeting, financial independence, and dynastic stewardship. We want our progeny to feel their responsibility with less stress. These discussions are far more important than adding a few more percentage points to our net worth.
Besides, once we hand over the money then it’s not ours anymore. Gifting means we give up the right to use our standards to judge people on what they do with their money. We’re happy to discuss it (if they want to) but they make the choices.
The 2026 IRS gift exclusion amount is $19K per gifter per recipient per year. (It rises every few years for inflation.) We’re deliberately spending down our wealth before starting Social Security in 2030 at age 70. We plan to do this for as long as we have reliable pension income and net rental income.
Philanthropy.
The second item on our abundance list is giving to charity. For us, the key to this growth has been quantifying and automating our process.
After a couple decades of experimentation, today this means that each year my spouse and I give away 1% of our net worth. (This seems sustainable because every year we still have 99% of our net worth left.) If a bull market drives up our wealth then we give a little more, and if a recession hammers us then… well, we might still give a little more to help those who got hammered even harder than us.
We send appreciated shares and cash to our donor-advised fund, where we can distribute anonymous annual grants to our local foodbank. (I also use our DAF to send all of my writing & speaking revenue to military-friendly charities.) While we send out the grants from the DAF every year, we occasionally bunch our contributions to take advantage of itemizing our deductions.
There are limits on annual charitable deductions, and we’re unlikely to bump up against that number. We’re certainly not interested in giving up our anonymity, let alone plastering our names on a building. Our DAF serves us very well.
Extravagance As We Get Older
Our abundance is more than our legacy of gifting & philanthropy. We’re also leaving room for frivolous fun.
It supports our aging bodies, our declining stamina, and our longer recovery times. Most of each category is under $10K/year, and a couple are only a few hundred dollars. Ironically our least-expensive extravagances deliver almost as much pleasure as the biggest one.
After gifting & philanthropy, here’s the rest of the list.
Third: first class airfare.
Whenever we’re flying commercial for longer than a few hours, we buy domestic first class or international business class. That works out to an additional $10K/year. Of course as military retirees we still enjoy the adventure of free military Space-A flights, especially stretched out on the deck of a C-17 cargo jet.
Yet we’re not tempted to go international first class with our own compartment, bed, and shower. A NetJets card is also not on our table.
Fourth: air conditioning.
In 2026 we added a $10,700 mini-split system with chillers in our four bedrooms.
This is despite living in a tropical climate, in a house that’s already filled with energy-efficient reflective-foil insulation. Our tropical tradewind breezes deliver plenty of cooling during the summer, but there are a few weeks in September-October where it’s nice to chill out in afternoons and hot nights.
This is a one-time splurge rather than lifestyle expansion. (We’ll clean and maintain the system on our own.) We’ll eventually add a few more (used, free) solar panels to our roof’s photovoltaic array to cover the extra electricity consumption. So far we’re still producing more power than we consume— our electric bill is $30/month for fees & taxes.
Fifth: massage therapy.
I stumbled across this extravagance when our (adult) daughter mentioned that our local physical therapy clinic offers sports-recovery deep-tissue trigger-point massages.
This is not a spa’s fluff & buff experience. This is heavy (steady) pressure by a licensed & experienced massage therapist on the knotted parts of your muscles which are already threatening to go into painful spasms. It releases a muscle’s trigger points and restores my mobility for several weeks.
Most of my massages look like a combination of an anatomy lecture (posture & repetitive motion) while also talking story. When we finish, I’m loosened up and flexible again.
After nearly two years of this routine, I haven’t had a single back or neck injury. I’ve maintained full range of motion in surfing, both on a longboard and a stand-up paddleboard. Even my acetaminophen consumption has dropped off.
Although I could apply to our VA clinic for a prescription (maybe?), the extravagance kicks in because I’m much happier at spending my own discretionary money without the VA’s bureaucracy. The massage therapists are happier too, because they can work on the parts which really need help for that session. They don’t have to document a patient’s progress toward a goal, and they don’t have to keep detailed records. They tell me what I need, and I get what we want.
On Oahu, a sports-therapy recovery massage every two weeks adds up to ~25 one-hour sessions per year at $90 each (including tip) = $2250/year.
Once again, the hedonic treadmill has turned this splurge into a lifestyle expansion. I plan to enjoy this therapy for the rest of my life.
Sixth: Slow travel in short-term rentals.
We no longer travel-hack a hotel rewards card, and a furnished 2BR apartment near public transport is perfect for the two of us. Compared to hotels, we spend maybe an extra $2500/year?
For a larger travel party, this might even be cheaper than a hotel. You’re not paying for parking fees, concierge services, or frequent housekeeping. You’re probably living like a local instead of paying resort prices for experiences, food, and beverages. You’re shopping in grocery stores, cooking in a kitchen, and spending more time in a neighborhood with interesting discoveries.
On the other hand, we once blew out our vacation budget by renting a centuries-old historic building in a foreign city where the bathroom’s marble floors are heated by the furnace’s hot-water piping. We did this in Spain’s central Sevilla, just a few blocks from the bullring and the cathedral, with weeks of things to see & do. Those memories are priceless.
My spouse and I don’t care about fine dining, so we think of short-term rentals as sleeping in our version of luxury while cooking for ourselves or eating in pubs.
Seventh: staycations.
I know, I know: we’re retirees and we’ve already lived in Hawaii for over half of our lives. Why would we need vacations?
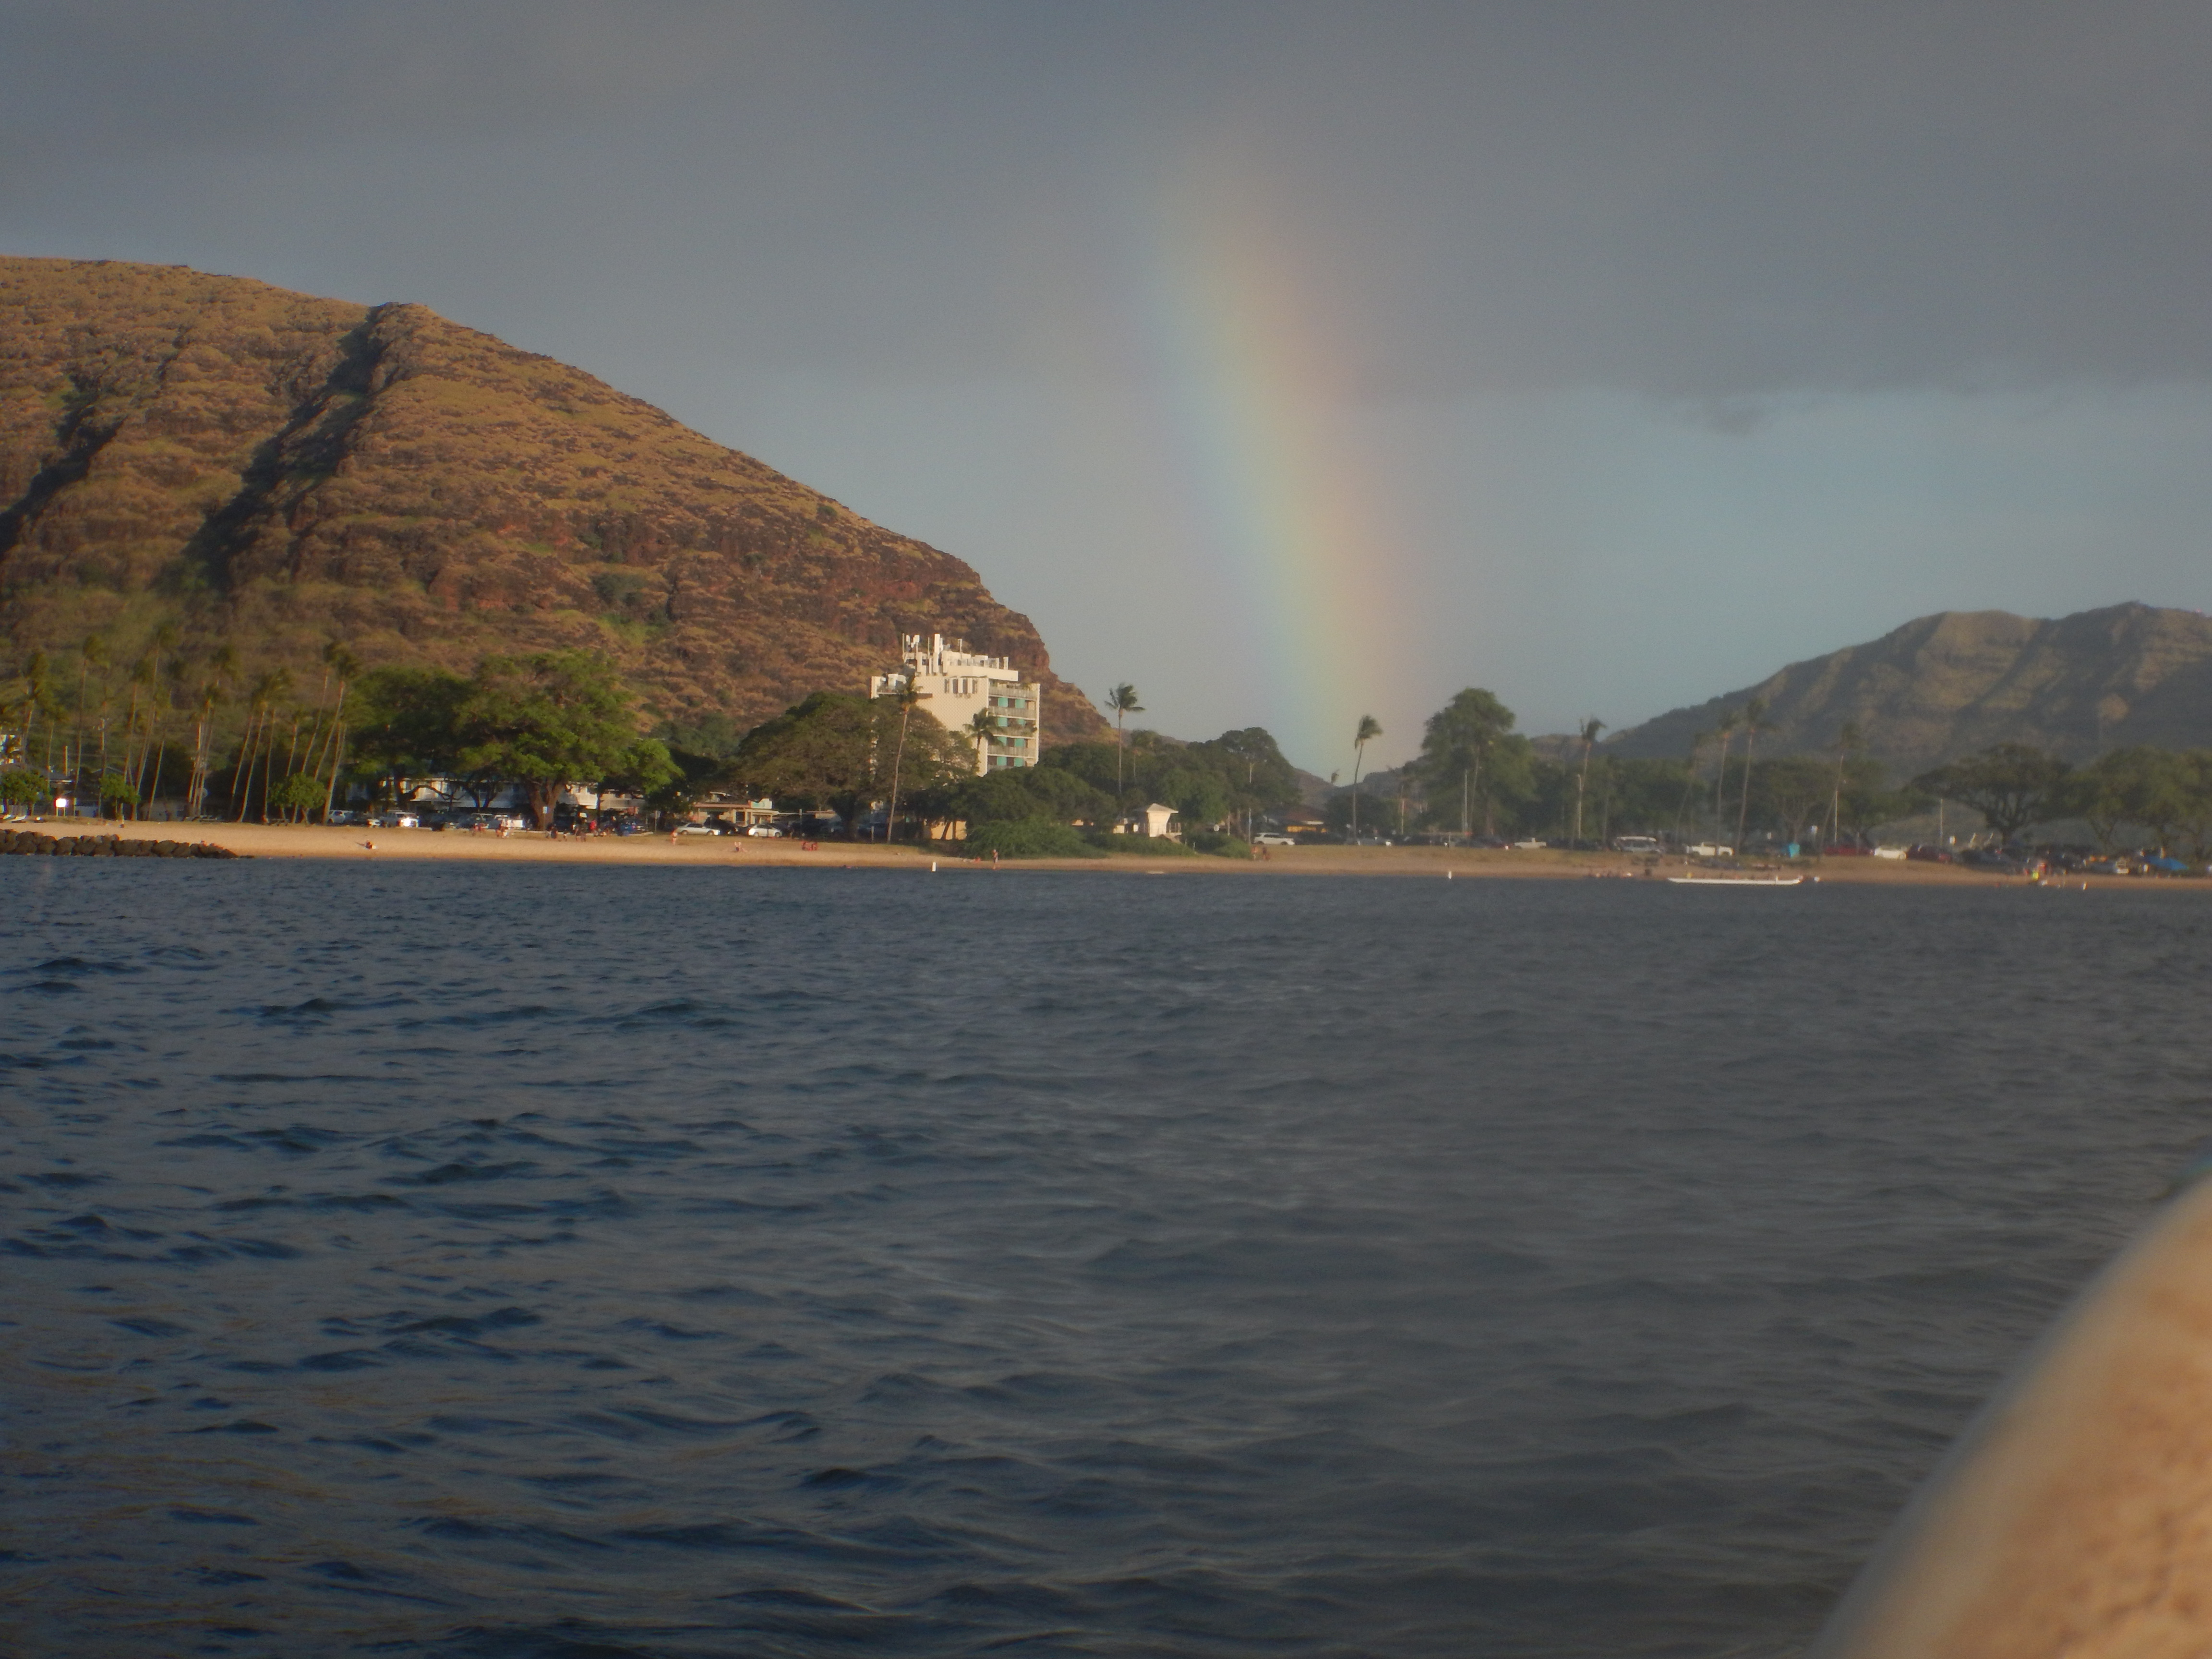
Surfing Pokai Bay, looking south
It’s a chance to get away from our daily lives by hiding taking a break from our house chores and yardwork at a rustic Oahu beach cabin. (I drafted this blog post in one.) Our favorite military recreation areas are the White Plains Beach cabins (in Kapolei) and Pilila’au Army Recreation Center’s beach cabins on Pokai Bay (in Waianae).
We do this 3-4 nights at a time, every 4-6 months, for an extra $2500/year.
Each time we stay in these beach cabins I update those posts for Poppin’ Smoke. (I guess that’s tax-deductible freelance “research” for travel blogging, but I’m not pushing the limits of my Schedule C income-tax deductions.) Along with enjoying the cabin and the beach, I write about living your financial independence— and I surf both dawn patrol plus sunset sessions for consecutive days.
We’ve even bought a couple of SCUBA dives on a charter boat from the Waianae Boat Harbor. It helps us tune up our skills for longer trips to Guam & Chuuk.
Eighth: better surfboards.
Lately when I’m paddling out my stand-up board (a 10-year-old Kazuma carbon-fiber, 9’8″x32″x4.5″, 160 liters) I find myself comparing its round nose to other pin-nose SUPs on my favorite surf break.
While I could do my usual shopping in Kimo’s used-SUP consignment inventory, I’m tempted go full retail on a Naish or a Blue Planet. I’ll still keep the Kazuma to enjoy the differences, but I’ll probably give away my high-performance (narrow & tippy) Aipa SUP.
Judging from the rest of my quiver, I’d use a new SUP for at least 15 years. This would probably cost $2500, but I’ll patiently accumulate more hours of practice (and skill) before I know what I want in a custom shape. Of course I’m happy to let a shaper guide me.
Will I upgrade from there to a hydrofoil board or even an eFoil? Well, that’s not out of the question yet. I’m not ready for one, and I’m not sure I care for the additional effort of rigging & maintaining one. However a hydrofoil board would certainly give my quads & hamstrings the workout needed to support my bone-on-bone knee joints.
The elders at our local surf breaks suggest that in 15 years (in my 80s), I’ll be thrilled to paddle out a longboard or a kayak. Maybe I’ll never get around to a foil.
Ninth: airport hotels.
This is recovering from travel in airport hotels… in the airport.
When we fly for conferences, meetups, and slow travel we’ve learned to arrive a day early and stay a day later to recover from jet lag and conference fatigue. (In my 60s, both of those have become significant realities.) It’s one more aspect of slow travel that helps avoid careless mistakes while maintaining our happy morale.
A hotel in the airport also avoids the entire logistics shuffle of “shuttle to the nearby hotel” and then “shuttle back to the airport”, the competition for shuttle seat signups, the waits at shuttle stops, and the inevitable traffic jams between lodging and airports. On slow travel it gives us a day to get oriented to our new location and scout out our AirBnB.
When your hotel’s already in the airport, you only have to walk an extra terminal from the airport arrival gate into the airport hotel lobby… and the next day, from the hotel to the airline’s check-in kiosk. Running late is not a problem.
It’s also better if I’m renting a car for that trip, because the rental garage is frequently close to the airport hotel. I’m even happier if we can use public transportation, and the airport is an easy stop.
I’m already spending the money to stay in a conference hotel or somewhere near the airport. This extravagance costs maybe an extra $1000/year?
Tenth: Skip the counter at the car rental.
After years of experimentation, I’ve settled on Hertz’s Gold Club rental cars. I still rent a car once or twice a year on the Mainland (mostly for financial conferences or meetups), and the Gold club means I can skip the counter. I can go straight from the airport to the rental lot and look for my name on the scoreboard. Sometimes the sedan that I reserved is parked in slot N82, and other times it’s “Pick anything you like from the President’s Row.”
This is a ridiculous luxury and probably costs me an extra $100 per rental, but the elimination of friction & hassle is priceless. There are no counter crowds or upsells, and I’m on the road at least 30 minutes faster.
Pro tip for you retirees flying military Space A: when we’re traveling through military passenger terminals we still use Enterprise rental cars. It was founded by a veteran who understands what we want for Space A roll calls. Most of the franchises still let you park their rental at the passenger terminal and then (after you’re on the flight manifest) put the keys in their drop box. I’ve called Enterprise many times from my seat in the jet as it taxies onto the runway for takeoff. Joint Base Hickam Pearl Harbor even has a Sixt franchise desk in their passenger terminal.
We estimate the Hertz Gold Club extravagance at $500/year.
Eleventh: boutique coffee.
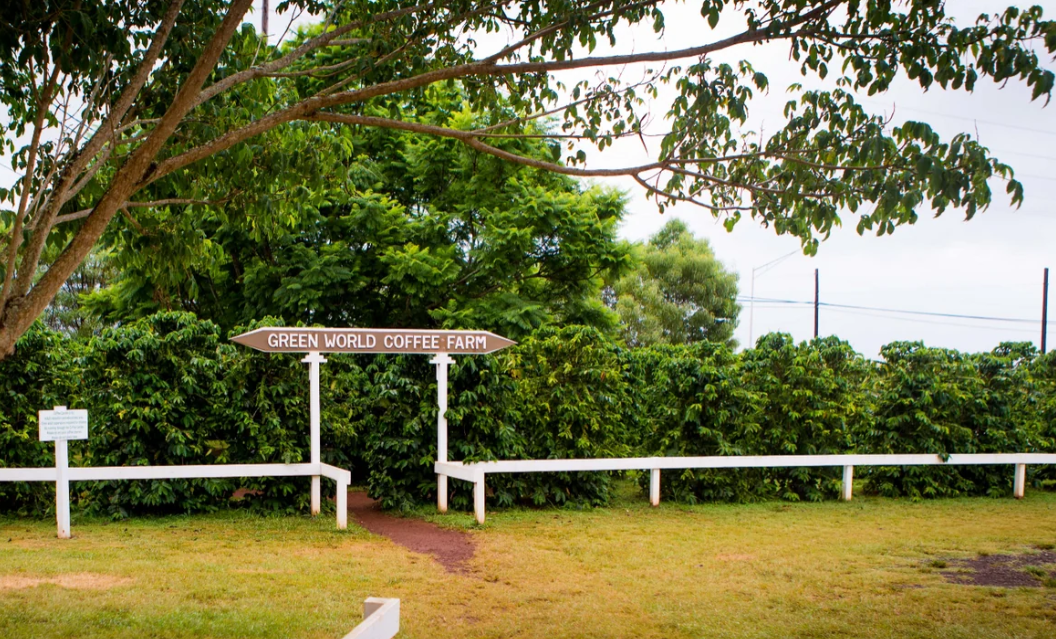
Personal-finance meetups held here.
Green World Coffee is a unique coffee shop in a decrepit 1960s pineapple warehouse a mile north of Wahiawa. They have coffee trees next to their parking lot, and they buy more beans from the farm on the hills along the road to Waialua.
It’s an awesome location for a business, and I smile every time I see the full parking lot. It’s only a few minutes away from my house, and it sits astride two of the most heavily-used highways between the North Shore & Central Oahu. (For example, on the way home after winter surfing at Haleiwa.) I try to avoid dropping in if there’s a visitor tour bus, but Green World has plenty of seating and they serve great coffee. I can always come back when the crowd dissipates.
Green World’s ground Kona makes a nice change from robusta beans. (I also drink French roast brands from Costco, Starbucks, or Peet’s.) I’m still in the stage of my life where it’s strong & black out of a Mr. Coffee machine, without enhancements like espresso or cappuccino brews. Yet I’m proficient with a French press or a moka pot too.
Green World is even more fun when our family hangs out there, and I enjoy watching our granddaughter chase around the feral chickens.
And yeah, 40 years ago I didn’t anticipate this ludicrous aesthetic. On sea duty I was swilling submarine engineroom coffee that boiled down in a five-gallon canister for the entire midwatch.
Buying two pounds of beans never seems to cost less than $60, and I buy there several times per year for a total of around $300/year.
12th and finally: Bandwidth.
When I have to buy bandwidth in airports, airplanes, or hotels then I’ll pay up for the faster speeds. (I don’t want to wait for Facebook to catch up with my photo uploads.) I frequently get upgraded for free with a Hilton or Marriott app, but I’m happy to pay.
This simple convenience is maybe an extra $100/year.
“Right, Nords, But What About Your Housecleaner?!?”
It’s complicated– we’ve experimented with this for three decades.
We started our family in 1992 while both of us were on active duty. In 1995, in a home that had become disgustingly disorganized & dirty, we admitted toddler-parenting defeat and hired a housecleaner. Life immediately got better, and our saved time went right back into more parenting.
We did this at the same time we were losing thousands of dollars per year on rent (beyond our housing allowance n San Diego) and in our net rental-property income (during a 1990s real-estate recession on Oahu).
In 2003 (back on Oahu, a year after I retired from active duty) we decided to try to clean our own house again. (This time our daughter was a teen, and she was much more help!) Our ambition lasted all the way up until late 2011 when we finished a familyroom renovation. We’d kept up with the cleaning around the construction site in the back of our home, while the rest of our home had gradually become covered in red dirt and drywall dust. We hired a housecleaner to help us “catch up”, and we quickly realized how much this improved our morale.
In 2019 our housecleaner quit the business, and we tried to do our own again. As empty nesters, we keep our home neat & organized– but we suck at cleaning horizontal surfaces. This time we only lasted a few years before hiring a new one.
We’ve learned that we’d rather outsource the housecleaning to let us do our own yardwork and home maintenance. It’s proven much easier to find a good weekly housecleaner than to hire a reliable weekly yard crew– let alone a handyman. We’re absolutely trading money for time, but the housecleaner is the least-expensive option. While they’re working in the house, we’re working on the house’s exterior and the yard.
We’re spending ~$5000/year on a housecleaner, and it’s moved from an extravagance to an essential expense. It’s the last bill we’d cut during another Great Recession, too.
What’s The Cost Of The Gifting And Philanthropy?
Gifting: over the next five years, we’re gifting approximately $800K of (advance) inheritance to our progeny. Our second grandchild, arriving in early 2027, is part of this amount.
(Sidebar: In a savage twist of irony, that’s still less than the life energy I burned on gutting it out to 20 for an active-duty pension. My fear, ignorance, and chronic fatigue kept me from exploring my options in the Reserves & National Guard, and that came with a high price tag.)
We feel strongly that young adults benefit from receiving a portion of their inheritance in their 20s & 30s— especially when the alternative is a dumpster-load of dollars in their 60s or 70s. We raised our daughter with an extensive curriculum of financial literacy (I can hear her rolling her eyes from here) and now she & her spouse are doing the same in their parenting.
Wait! Build your financial literacy first.
If I’d been gifted tens of thousands of dollars as a teen, I certainly know what I would have done (in my negligible financial literacy) with that much money dumped on my head. We grandparents see it as our job (“We have one job!”) to develop our grandkids’ financial literacy (in age-appropriate ways) to guide them to better choices than we did. Fortunately for them, my childhood financial literacy sets a very low bar.
They’re all going to get this money through gifting (while we’re alive) or inheritance (much later). We feel that it’s most useful when we can talk about the options (no judging!) instead of attempting to control their decisions from our wills or trusts.
In 2031 we’ll take another look at our gifting plan. Maybe we’ll keep it up, maybe we’ll change the amounts, or maybe we’ll find another place for the money. Even when you’re in your 60s (and reminded of the mortality of your parents), this is very much a personal experiment in learning how to *let go.*
I have to admit that it just makes me tired to think about designing a system of pulling on those paperwork purse strings after I’m dead. I’d rather talk about personal finances and stewardship while we’re alive. (I write about these topics in my family e-mails titled “GrandDoug’s Weekend Links.”) I’ll still leave behind a financial love letter after I’m dead, but… I’ll be dead.
Philanthropy: during the rest of our lives, our 1%/year looks like about $35K/year (today’s dollars) for at least the next 20 years.
Because we’re chronic optimizers, this year we’ve learned to coordinate our DAF’s grant to our foodbank with their annual Food Day matching campaign. Our donation is working twice as hard from other donors matching our grant.
I might be a little competitive about our philanthropy, but this seems like the right outlet for that behavior.
“What’s The Cost Of All This Extravagance?”
We’ll separate the accounting into one-time splurges and lifestyle expansion.
Our air-conditioning comfort and my surfboard enthusiasm add up to a splurge of $13,200. That’s a fraction of our annual gifting & philanthropy, and a rounding error on our net worth.
We’ve still budgeted for essential lumpy expenses. We’ll continue to take care of our home (and maybe add a new roof?), and we’ll probably still buy a new-to-us used auto every decade or so. (I might only drive for another 10-15 years before switching to UberLongboard.) Alongside the long-term maintenance expenses, these splurges seem reasonable.
On the other hand, we’ve all been warned about the dangers of lifestyle expansion. How much longer can we continue our splurging frivolity before we’re in danger of rationing our Social Security deposits and dumpster-diving for our food?
Woah: that total is $19,150/year.
But wait, that’s also a fraction of our annual gifting and our philanthropy. If we keep up that lifestyle expansion during the next 20 years then we’re looking at nearly $385K in today’s dollars.
I can’t help but notice that much of our lifestyle expansion is related to travel, which (unfortunately) won’t go on forever. Travel expenses can be a challenge during our go-go years, but I already see our slow-go years creeping up over our horizon. 20 years from now in 2046 I’ll be… yikes, 85 years old… and I suspect that by then I’ll be closer to my no-go years.
Your Call To Action
While you’re on your path to financial independence, then keep going. (Even when it’s in the boring middle.) Focus on your own work/life balance, your quality of life, and your values. Don’t compare your journey to this blog post or to other people.
When you’re close to financial independence, it’s time to think about your own ‘enough’ and abundance lists. Budget for your stewardship (like gifting your family or donating 1% of your net worth each year to charity) and consider sharing any inheritance while you’re still alive.
You already know what you’d do if you encountered a nasty recession. Catastrophizing is a necessary mental & emotional exercise for planning how you’ll get through tough times, but when you’re near FI then you’re also much more resilient. If you’re not using the 4% Safe Withdrawal Rate then you can still check your guardrails on your spending.
Next, plan for your fun! In your abundance, where would you splurge? What would you spend every year (while you still can) to expand your lifestyle? You don’t have to share your personal lives here (unless you want to) but feel free to call me out in the comments on anything I’ve overlooked.
There are no affiliate links or paid ads in this post. Try your military base library or local public library before you pay money for these books– in any format.
Military Financial Independence on Amazon:
 |
|
Raising Your Money-Savvy Family on Amazon:
 |
|
Related articles:
Ramit Sethi’s Rich Life website
What If The 4% Safe Withdrawal Rate Fails?!?
Who Will Be Millionaire Interview #500 On ESIMoney?
Die With Zero (Kindle edition)
What It Feels Like To Give Away $2M After Financial Independence
Rob Berger’s Financial Love Letter (5:15 in the video)